Our Method

The Loan Resolution Protocol

A transparent, legally secure 4-step debt settlement framework designed to take every loan borrower from immediate debt collection distress to a final, formal credit settlement.

STAGE 01

Secure Case Onboarding & Document Audit

The protocol starts with a thorough review of your outstanding financial debt liabilities, active loan recovery notices, and overall repayment capabilities.
Advisor onboarding a borrower's case and reviewing documents
Upload outstanding loan statements and bank notices securely via the AES-encrypted Member Portal.
01
Conduct a detailed debt-to-asset audit to determine a realistic settlement or restructuring capability.
02
Assign a dedicated financial mediator and empanelled banking advocate to your file.
03
ESTIMATED TIMELINE 1 to 3 Days
Step Onboarding Active
Secure Audit Engine Auditing
Document Verification Verified
Interest Audit Scan Active
Advocate Matching Pending
Audit Completeness: 78%
PROTECTION STRENGTH 99.8% Block Rate
Firewall Active
Creditor Call Routing Active Protection
Agent Calls Blocked 184 Calls
FPC Cease & Desist Notices Dispatched
Lenders Contained: 9 of 9
STAGE 02

Legal Representation & Harassment Containment

We immediately deploy statutory safeguards to block recovery agents and route all official communications through our legal division.
Legal team dispatching harassment containment representation notices
Dispatch legal representation notices under the RBI Fair Practices Code to your lenders.
01
Direct lenders to route all calls, visits, and settlement proposals through our empanelled advocates.
02
Provide immediate relief against threatening calls, harassment, and off-hour creditor visits.
03
STAGE 03

Bilateral Settlement Negotiation

Our resolution team initiates compromise meetings, challenges inflated interest rates, and structures formal One-Time Settlement (OTS) offers.
Advocates negotiating a bilateral settlement with bank committee
Draft and submit formal compromise offers backed by precedent cases and financial audits to bank recovery heads.
01
Conduct face-to-face or committee-level mediation meetings to negotiate optimal principal waivers.
02
Contest and eliminate illegal penalty charges, compounded interest, and recovery commissions.
03
ESTIMATED TIMELINE 30 to 90 Days
Negotiations in Progress
Settlement Target Engine Active
Initial Claim 100%
Waiver Target 65% Waiver
Payable (35%) Waived (65%)
Committee Review Proposal sent to bank board
CLOSURE STATUS Assets Vetted
Protection Complete
Asset Handover System Releasing
OTS Letter Vetted Approved
No Dues Certificate (NDC) Retrieved
Mortgaged Title Deeds Releasing
Overall Resolution: 100%
STAGE 04

Final Compromise Approval & Asset Release

We finalize settlement agreements, manage structured payouts, and retrieve your mortgaged property deeds from bank custody.
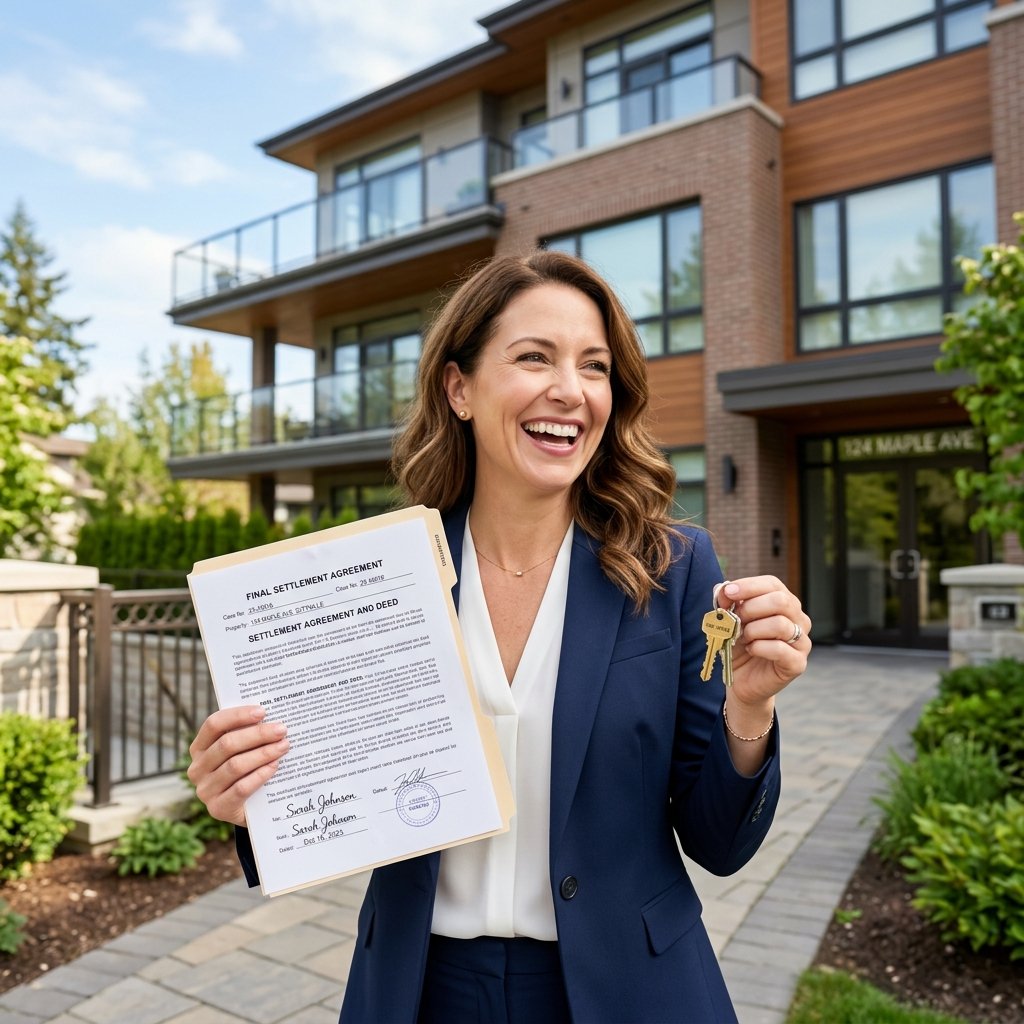
Borrower reviewing final settlement approval and released documents
Verify and vet the formal One-Time Settlement (OTS) letter issued by the bank committee.
01
Confirm execution of payment terms and retrieve the No Dues Certificate (NDC).
02
Oversee the release of all original title deeds, mortgaged documents, and NOC dispatches.
03
Legal Literacy

Know Your Rights as a Borrower in Default

Defaulting on a loan is a civil distress, not a criminal offence. The Reserve Bank of India (RBI) has established strict parameters to protect borrower dignity and secure fair legal hearings.

Right to Fair Treatment

Lenders and recovery agents are strictly prohibited from using abusive language, physical intimidation, or defaming you before family and neighbors.

Right to Communication Timing

Recovery agents can only call or visit your premises between 8:00 AM and 7:00 PM. Contacting you outside these hours violates RBI regulations.

Right to Representation

You have the absolute right to direct lenders and recovery agents to communicate through your authorized legal representative.

RBI Fair Practices Code Enforcement

“Lenders shall not resort to harassment or intimidation. All recovery notices must give borrowers sufficient time to object.”

RBI Guidelines Ombudsman Protected

Our legal containment division logs all guideline violations and raises complaints directly with the RBI Banking Ombudsman to secure interest cuts and penalties on non-compliant banks.

Take Control of Your Resolution Journey Today

Register for our Aegis Protection program. Secure complete containment, deploy stops on harassment, and assign a negotiator.